How I Got a Wrong Shriram Finance Loan Removed from My CIBIL Report

Very recently, a commercial vehicle loan from Shriram Finance showed up on my CIBIL report, even though I have never taken a Shriram Finance loan. The account looked real enough to worry a future lender: sanctioned at ₹53,000 with a running balance, reported as an individual commercial vehicle loan. I was travelling when I spotted it on 23 August 2026, so the fix had to be remote: email Shriram Finance’s grievance desk, raise a formal CIBIL dispute the same day, and wait for both sides to reconcile. CIBIL confirmed removal on 1 September 2026—nine days later. Shriram Finance’s own written confirmation only arrived on 17 September, more than two weeks after the tradeline was already gone.
Make monthly CIBIL checks a habit
I now pull my CIBIL report at least once a month. It takes a few minutes once you are enrolled on myCIBIL, and it is the fastest way to catch problems before you apply for a new card or loan.
- Loans or credit cards you never opened: sometimes identity theft, sometimes a data mix-up.
- Accounts closed years ago still showing as active or overdue.
- Wrong PAN, mobile number, or address tied to your profile (another person’s file bleeding into yours).
- Hard enquiries you did not authorise, often the first sign someone applied in your name.
Mistakes come from three directions: fraud or identity theft, incorrect reporting by the credit bureau, and incorrect reporting by the lender. You fix all three the same way: document the error, dispute with CIBIL, and notify the institution that reported the account.
What showed up on my report
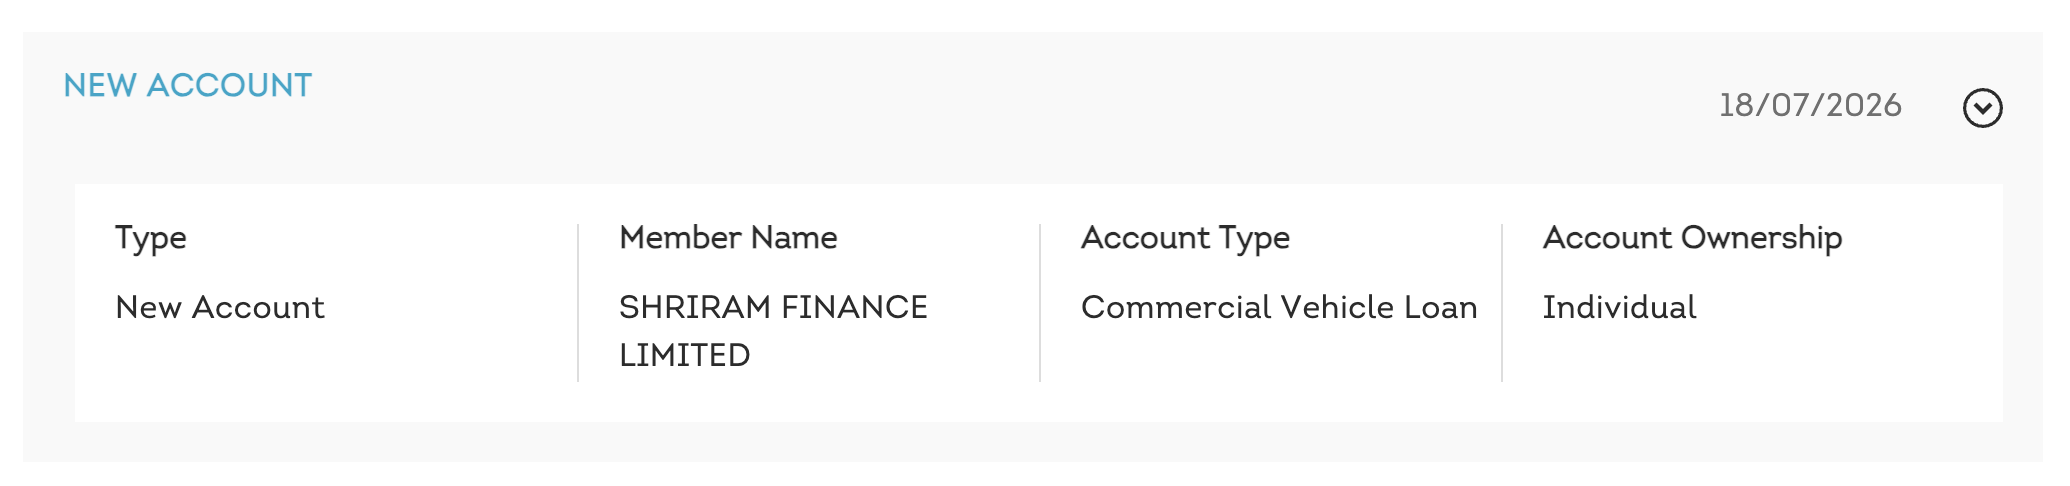
The entry was a Shriram Finance Limited commercial vehicle loan, reported as Individual ownership on 18 July 2026. I had no relationship with Shriram Finance, no loan agreement, and no EMI debits. Yet the account sat on my report as if I were the borrower.
Others reporting the same Shriram Finance pattern on Reddit
When I searched after spotting my own entry, I found active threads from other Indians hitting the same wall. Ghost Shriram Finance vehicle or auto loans on CIBIL, often with score drops and stalled card or loan applications:
Step 1: Raise a dispute on CIBIL
CIBIL cannot delete a lender-reported account on its own. Under the Credit Information Companies (Regulation) Act, corrections need confirmation from the reporting institution. What CIBIL does is route your dispute to that lender and track the investigation.
- Log in to myCIBIL (or enroll if you are new): https://www.cibil.com/
- Open your latest credit report and go to the dispute centre.
- Select Account Information and pick the loan you do not recognise.
- Mark the dispute reason, typically “account does not belong to me” or “never applied for this facility”.
- Submit and save the dispute reference number. CIBIL emails updates from [email protected].
Step 2: Email Shriram Finance’s grievance desk
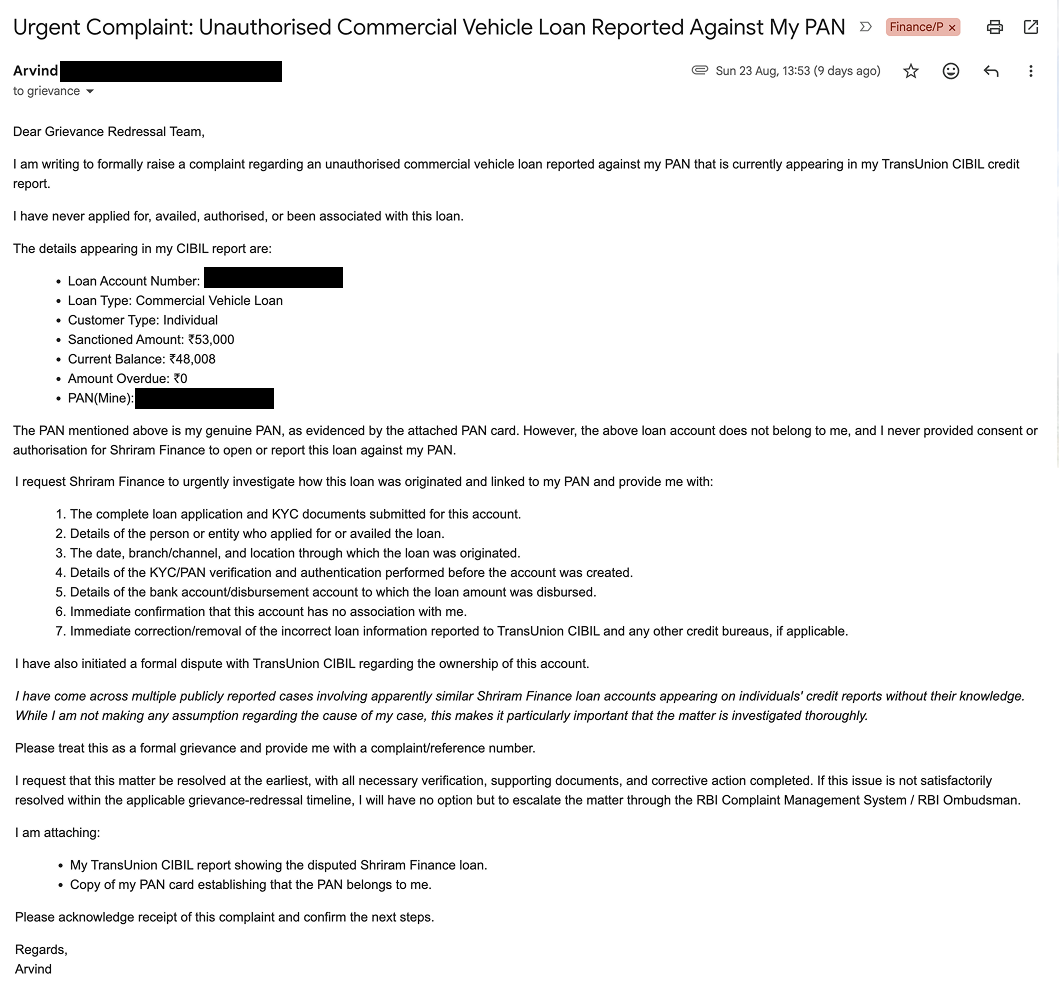
In parallel, I emailed [email protected] on 23 August 2026 with subject line “Urgent Complaint: Unauthorised Commercial Vehicle Loan Reported Against My PAN”. The email listed the loan type, sanctioned amount (₹53,000), current balance, and account number exactly as on CIBIL; stated I had never applied or authorised the facility; asked Shriram to share KYC and disbursement details for the real applicant; and requested immediate deletion from CIBIL and other bureaus. I attached my CIBIL report screenshot and PAN copy.
| Channel | Contact | When to use |
|---|---|---|
| Shriram Finance grievance | [email protected] | Wrong tradeline, closure/NOC issues, bureau mismatches |
| Shriram Finance customer care | [email protected] / 1800-103-4959 | First log of the issue; keep the reference number |
| CIBIL consumer helpline | +91 22 6140 4300 (Mon–Sat, 10 am–6 pm) | If the online dispute form fails or you need status |
| CIBIL general queries | [email protected] | Follow-up with dispute ID and CIBIL control number |
Attach a PDF or screenshot of the CIBIL page showing the wrong account, a copy of your PAN, and any prior acknowledgement from CIBIL. Keep subject lines explicit: “Credit bureau correction — loan account not mine — [Your name] — [Account number as on CIBIL]”.
Step 3: Track both threads until the tradeline disappears
- Watch for CIBIL dispute status emails, usually “in progress” until the lender responds.
- If Shriram Finance replies with an internal ticket number, reply-all with that number whenever you chase CIBIL.
- After the lender confirms deletion to the bureau, pull a fresh CIBIL report (allow a few days for the database to refresh).
- Save the final clean report PDF. You may need it if the ghost loan reappears.
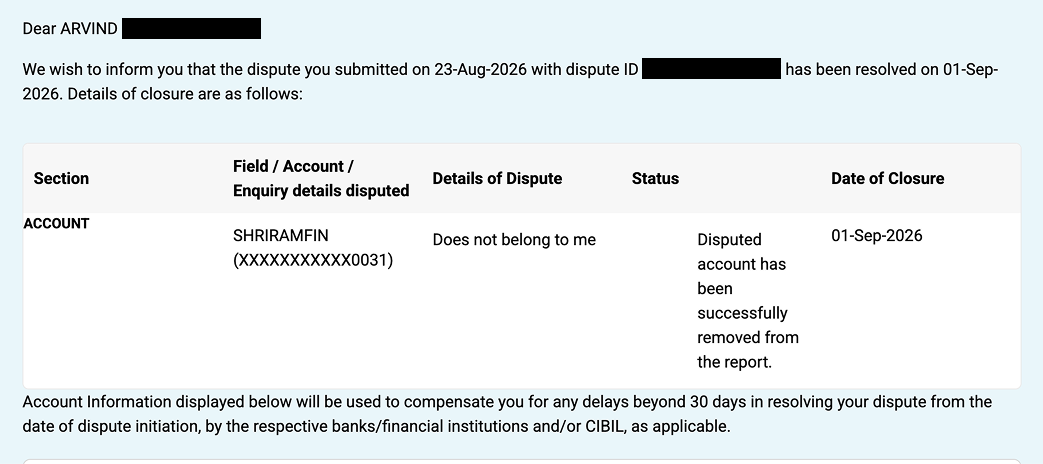
In my case, CIBIL emailed on 1 September 2026 that the disputed Shriram Finance account “has been successfully removed from the report”, nine days after I raised the dispute on 23 August. That is faster than the 30-day RBI guideline, but timelines vary with lender responsiveness. If nothing moves after 30 days, escalate to Shriram Finance’s nodal officer (listed on their grievance policy page) and consider RBI CMS at https://cms.rbi.org.in for a formal complaint record.
Update: Shriram Finance confirmed the correction in writing
The bureau side closed first. Shriram Finance replied separately on 17 September 2026, 25 days after my grievance email, with a complaint ID logged against the same loan account. Their words: they had “taken it up for necessary rectification to all credit bureaus and awaiting their confirmation”, and I should check my latest credit report after three working days.
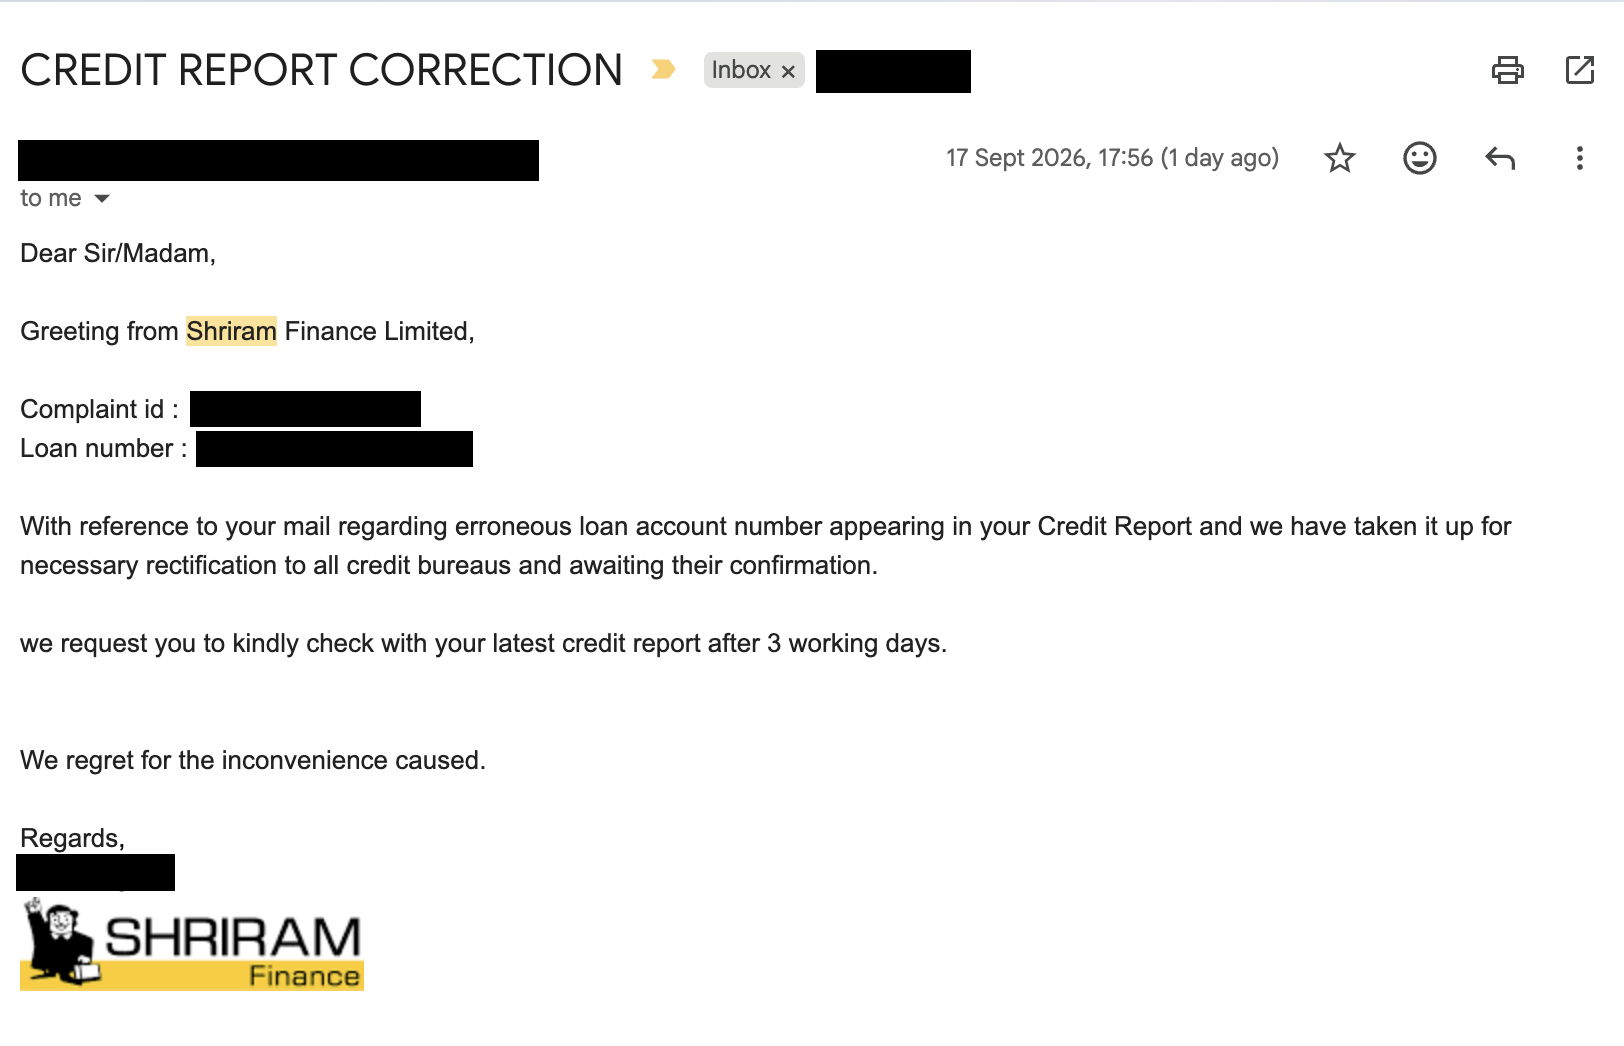
Two things are worth taking from that reply. The correction goes to every bureau the lender reports to, not just CIBIL, so this email is also your evidence for Experian, CRIF High Mark and Equifax. And the two clocks run independently: CIBIL had already deleted the tradeline on 1 September, while the lender’s formal acknowledgement landed on 17 September. Silence from the lender does not mean nothing is moving, so keep both threads alive until you see a clean report.
Save this email along with the complaint ID. If the same account resurfaces on any bureau later, the lender’s written admission plus your clean report settles it in one reply instead of another 30-day dispute cycle.
If the wrong loan is from another lender
The playbook is identical: CIBIL dispute plus an email to that bank or NBFC’s grievance officer with PAN, account number, and proof you are not the borrower. For credit cards, also check whether someone added you as an add-on without your knowledge. For co-borrower or guarantor errors, send the bureau any document showing you never signed.
Quick FAQ
Does disputing CIBIL cost money?
No. Dispute resolution is free on CIBIL’s consumer portal. Ignore paid “CIBIL repair” services that promise instant deletion. They cannot bypass the lender confirmation step.
Will disputing hurt my score?
Raising a dispute does not lower your score. Removing a fraudulent or incorrect overdue account usually helps once the tradeline is deleted.
Should I also check Experian, CRIF, or Equifax?
Yes, if you are about to apply for credit. Some lenders pull bureaus other than CIBIL. After Shriram confirms a correction, ask which bureaus they updated, or pull a consolidated report if your bank provides one.
What if I am mid card application and discover the error?
Pause the application, file the dispute immediately, and inform the bank’s credit ops team with your dispute reference. Re-applying after the clean report saves a hard enquiry decline on record.